Buying a Manufactured Home: 7 Things You Need to Check First
Quick answer
Manufactured homes can be financed, but the process looks different. Here's what buyers need to know before making an offer.
REALTOR® with RE/MAX Journey and Mortgage Loan Originator, NMLS #2603041. Bilingual homeownership education with a local focus on Rutherford County and Western North Carolina.
Buying a Manufactured Home: 7 Things You Need to Check First
Manufactured homes CAN be financed.
But the process can look a little different from buying a traditional stick-built home.
And this is where buyers sometimes get surprised.
First, let's clear up something important:
A manufactured home is not the same thing as a modular home.
A modular home is generally treated much more like a traditional site-built home.
A manufactured home is built to federal HUD construction standards, transported to the property on a permanent chassis, and has some additional requirements that we have to verify.
So what are we looking for?
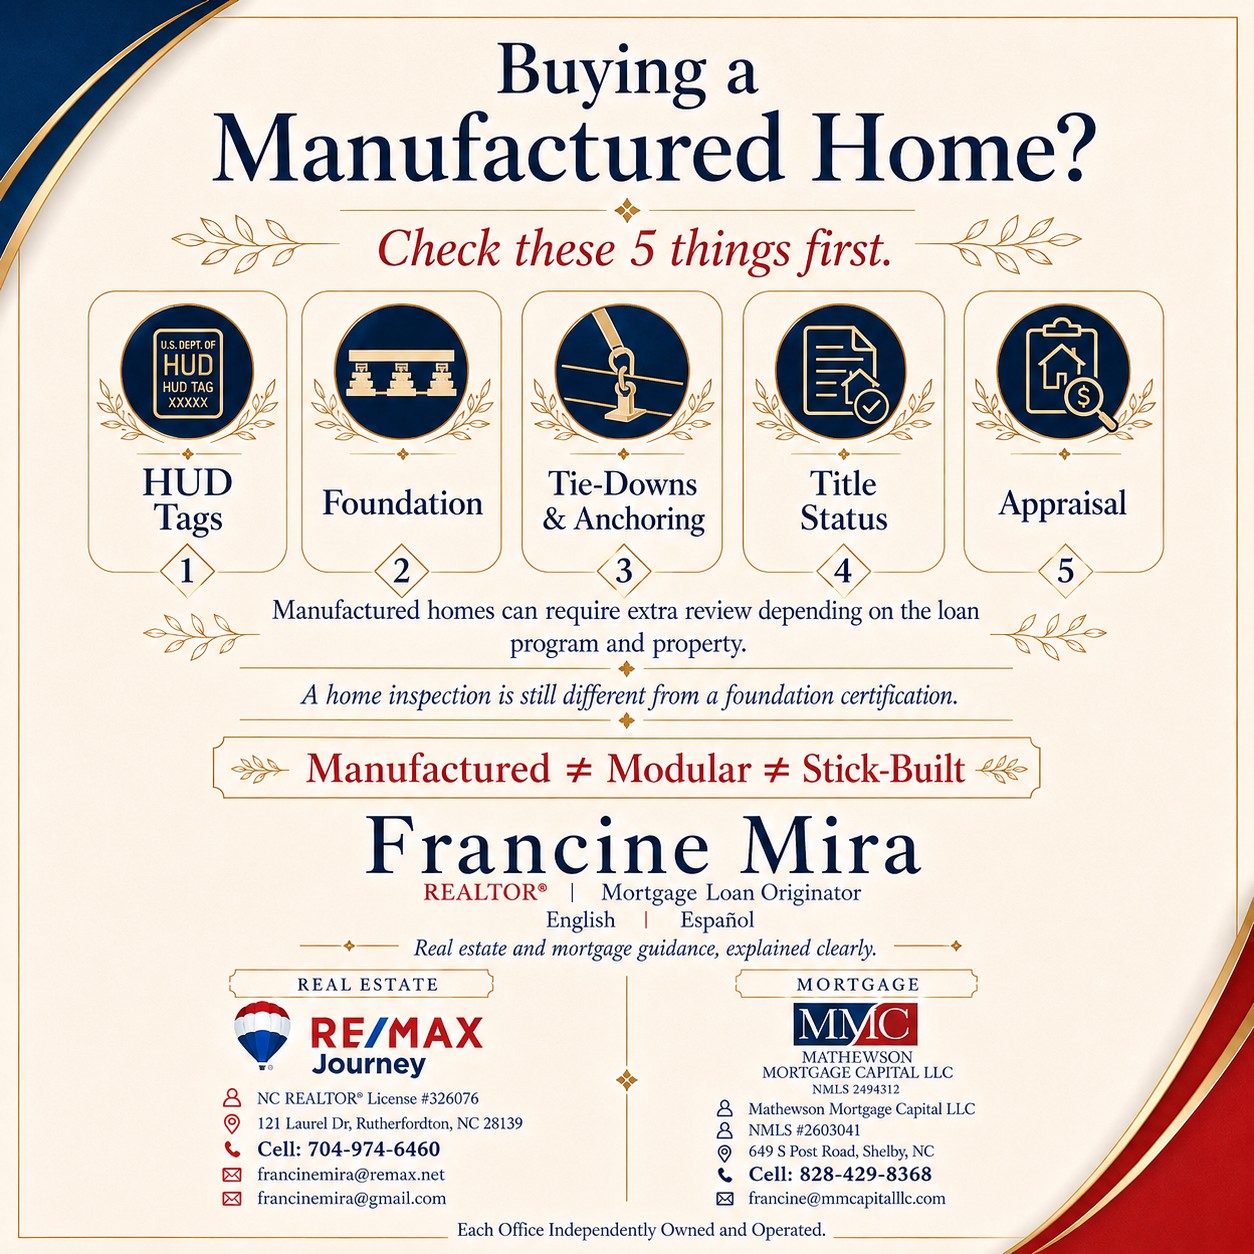
1. HUD Tags and Data Plate
Manufactured homes built after June 15, 1976 should have HUD certification labels attached to the home.
There is also normally a data plate inside the home showing information such as the manufacturer, model, serial numbers and certification information.
Missing tags do not automatically mean the transaction is impossible, but they can create extra steps.
2. The Foundation Matters
For many manufactured-home loans, we need to verify that the home is permanently installed and that the foundation meets the requirements of the particular loan program.
Depending on the loan, a licensed engineer or registered architect may need to inspect the foundation and provide a certification.
This is one of the biggest differences from a typical stick-built purchase.
3. Tie-Downs, Anchoring and Setup Matter
Manufactured homes have specific installation requirements.
The anchoring system, support system, drainage, utilities and overall installation may need additional review.
You may hear terms like:
- Foundation certification
- Engineer inspection
- Tie-down inspection
- Permanent foundation
- HUD-compliant installation
That is normal in manufactured-home lending.
4. The Title Has to Be Checked
In North Carolina, a manufactured home may begin as titled personal property, similar to a vehicle.
When it becomes permanently affixed to land, there is a legal process that can allow the title to be surrendered and the home to become part of the real property.
That paperwork matters.
Before assuming a manufactured home is ready for traditional mortgage financing, we need to know:
- Who owns the land?
- Is there still a DMV title?
- Was the title properly surrendered?
- Is the home legally considered real property?
Those questions can make or break a transaction.
5. The Appraisal Is Different
The appraiser is not simply comparing the home to any house nearby.
Manufactured-home appraisals have specific requirements and the appraiser may need to identify things such as:
- HUD labels
- Data plate information
- Manufacturer
- Serial numbers
- Number of sections
- Foundation and installation characteristics
- Comparable manufactured-home sales
If the appraiser sees a foundation or property concern, additional inspections may be required.
6. You Still Want a Regular Home Inspection
An engineer's foundation certification is NOT the same thing as a buyer's home inspection.
I would still want my buyer looking at the overall condition of the property:
- Roof
- HVAC
- Plumbing
- Electrical
- Moisture
- Floor system
- Windows and doors
- Water and septic systems
- General safety and maintenance concerns
Each inspection has a different purpose.
7. The Loan Program Matters
FHA, VA, USDA and Conventional programs can all have different manufactured-home guidelines.
Age of the home, foundation, property classification, whether it has been moved, condition, appraisal findings and other factors can affect eligibility.
That is why I never like to tell someone:
"It's a manufactured home, so yes, it qualifies."
We need to review the actual home.
The Biggest Takeaway
Manufactured homes are absolutely a homeownership option.
They just require us to do a little more homework upfront.
And I would much rather figure out the HUD tags, title, foundation and financing requirements BEFORE you spend money on inspections, due diligence and an appraisal.
That is where having your REALTOR® and lender communicating early can save a buyer a lot of stress.
Francine Mira | REALTOR®
RE/MAX Journey
NC REALTOR® License #326076
121 Laurel Dr., Rutherfordton, NC 28139
Cell: 704-974-6460
francinemira@remax.net
francinemira@gmail.com
Francine Mira | Mortgage Loan Originator
Mathewson Mortgage Capital LLC
Company NMLS #2494312
Francine Mira NMLS #2603041
649 S Post Road, Shelby, NC
Cell: 828-429-8368
francine@mmcapitalllc.com
Each Office Independently Owned and Operated.
Loan eligibility and property requirements vary by loan program, lender guidelines and the individual property.
#FrancineMira #ManufacturedHomes #ManufacturedHomeFinancing #HomeBuyingEducation #MortgageEducation #RealEstateEducation #FirstTimeHomeBuyer #RutherfordCountyNC #WesternNorthCarolina
Still have a question?
Ask Francine. I’ll help you understand what your next step should be.