Due Diligence Money vs. Earnest Money: What North Carolina Buyers Need to Know
Quick answer
Due diligence money and earnest money are NOT the same thing in North Carolina. Here's what every buyer needs to understand before making an offer.
REALTOR® with RE/MAX Journey and Mortgage Loan Originator, NMLS #2603041. Bilingual homeownership education with a local focus on Rutherford County and Western North Carolina.
Due Diligence Money vs. Earnest Money: What North Carolina Buyers Need to Know
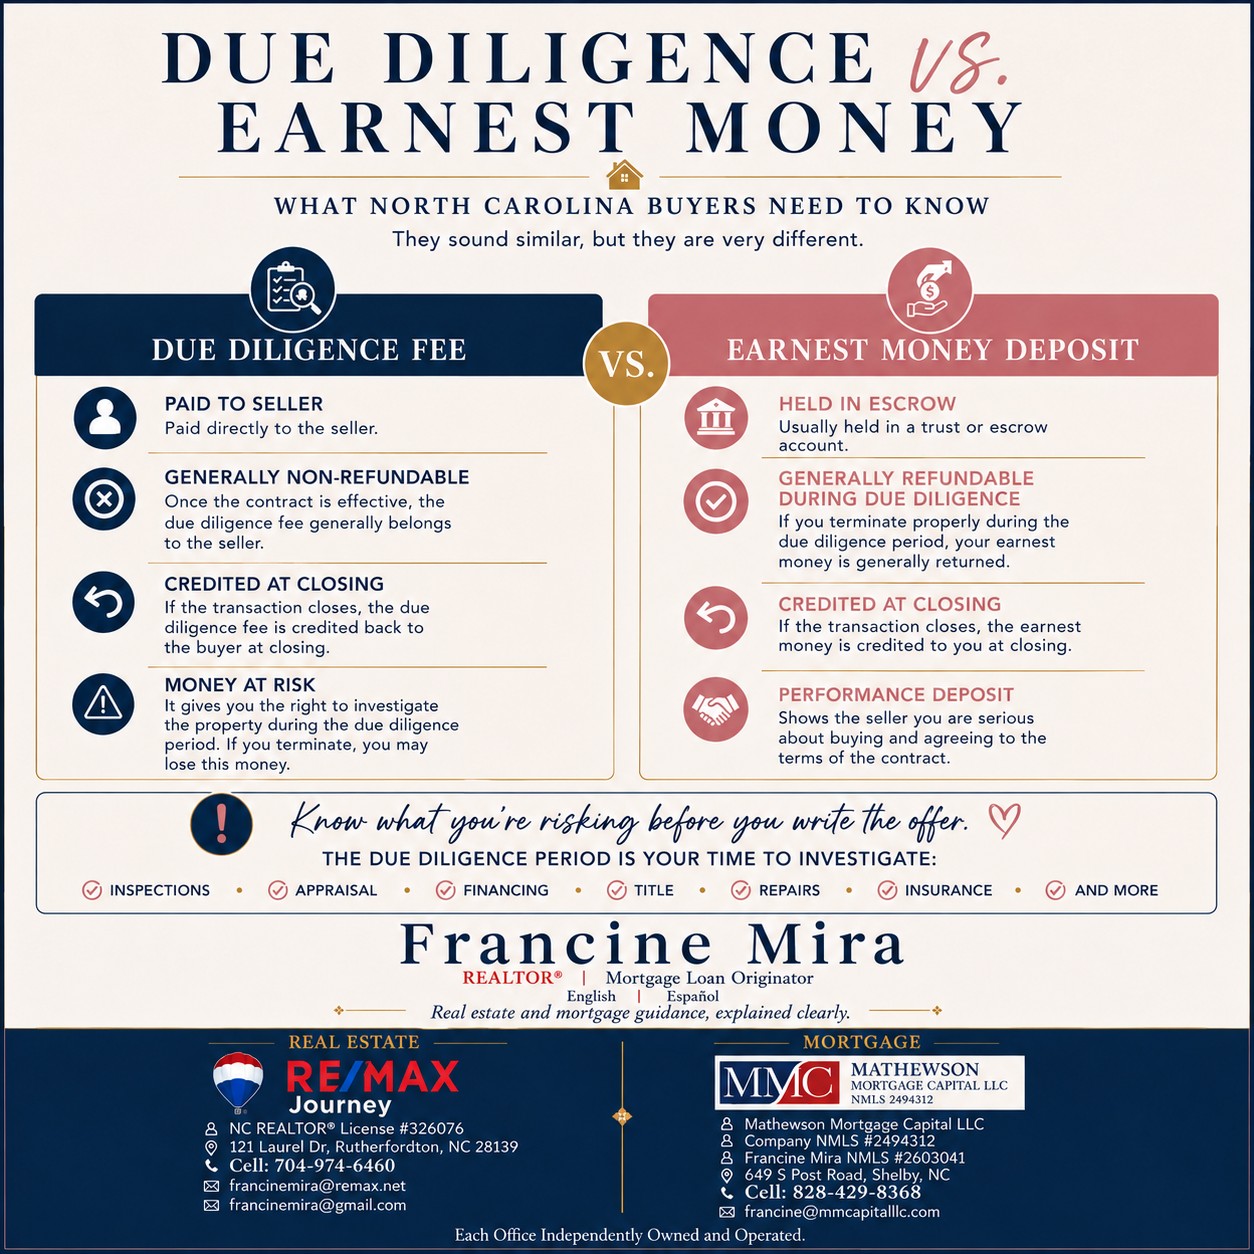
Due diligence money and earnest money are NOT the same thing in North Carolina.
And if you're buying a home here, this is something you really need to understand before making an offer.
Let's break it down simply.
Due Diligence Fee
The due diligence fee is a negotiated amount the buyer pays directly to the seller.
It gives the buyer the right to investigate the property during the agreed due diligence period and, under the standard NC contract, terminate for any reason or no reason during that period.
Here's the part buyers need to pay attention to:
Once the contract becomes effective, the due diligence fee generally belongs to the seller.
If you decide during due diligence that you no longer want the house, you can usually terminate, but you may lose that money.
If the transaction successfully closes, the due diligence fee is credited back to you at closing.
So think of due diligence money as:
Money you are putting at risk for the opportunity to investigate the property and move forward with the contract.
Earnest Money Deposit
Earnest money is different.
It is generally held in a trust or escrow account rather than being immediately paid to the seller.
It shows the seller that you are serious about purchasing the home.
If you terminate the contract properly during the due diligence period, the earnest money is generally refundable under the standard contract.
If you move past the due diligence deadline and later fail to close without a contractual right to terminate, your earnest money may be at risk.
So think of earnest money as:
A good-faith deposit connected to your performance under the contract.
A Simple Example
Here's a simple example:
You offer on a home with:
- $2,000 Due Diligence Fee
- $1,000 Earnest Money Deposit
Then you complete your inspection and discover something you are not comfortable with.
If you terminate properly before the due diligence deadline:
- You may lose the $2,000 due diligence fee.
- But your $1,000 earnest money would generally be returned.
That's a $2,000 financial decision.
Make an Offer That Makes Sense for YOU
And this is why I never want a buyer choosing a due diligence amount simply because:
"That's what will make the offer look good."
Yes, your offer needs to be competitive.
But your offer also needs to make financial sense for YOU.
Before deciding how much due diligence money to offer, think about:
- How competitive the property is
- How long you need for inspections
- Whether financing and appraisal are involved
- The condition of the home
- How much money you can comfortably afford to lose
- Your overall cash available for the transaction
The Due Diligence Period
And remember...
The due diligence period is when we may be working through:
- Home inspection
- Termite inspection
- Septic inspection
- Well and water testing
- Survey
- Repair estimates
- Appraisal
- Loan approval
- Insurance concerns
- Title questions
- And anything else we need to learn about the property
That deadline matters.
Protecting Your Money
As your REALTOR®, one of my jobs is making sure you understand what you're agreeing to BEFORE your money is on the line.
Winning the house is exciting.
But protecting your money matters too.
Francine Mira | REALTOR®
RE/MAX Journey
NC REALTOR® License #326076
121 Laurel Dr., Rutherfordton, NC 28139
Cell: 704-974-6460
francinemira@remax.net
francinemira@gmail.com
Francine Mira | Mortgage Loan Originator
Mathewson Mortgage Capital LLC
Company NMLS #2494312
Francine Mira NMLS #2603041
649 S Post Road, Shelby, NC
Cell: 828-429-8368
francine@mmcapitalllc.com
Each Office Independently Owned and Operated.
This is general educational information. Contract terms are negotiable and individual circumstances vary.
Still have a question?
Ask Francine. I’ll help you understand what your next step should be.