Large Deposits Can Create Big Questions During Underwriting
Quick answer
It's not that the lender thinks the money isn't yours — it's that they need to document where it came from. Here's what to know.
REALTOR® with RE/MAX Journey and Mortgage Loan Originator, NMLS #2603041. Bilingual homeownership education with a local focus on Rutherford County and Western North Carolina.
Large Deposits Can Create Big Questions During Underwriting
And no, it's not because the lender thinks the money isn't yours.
It's because the lender may need to document where the money came from.
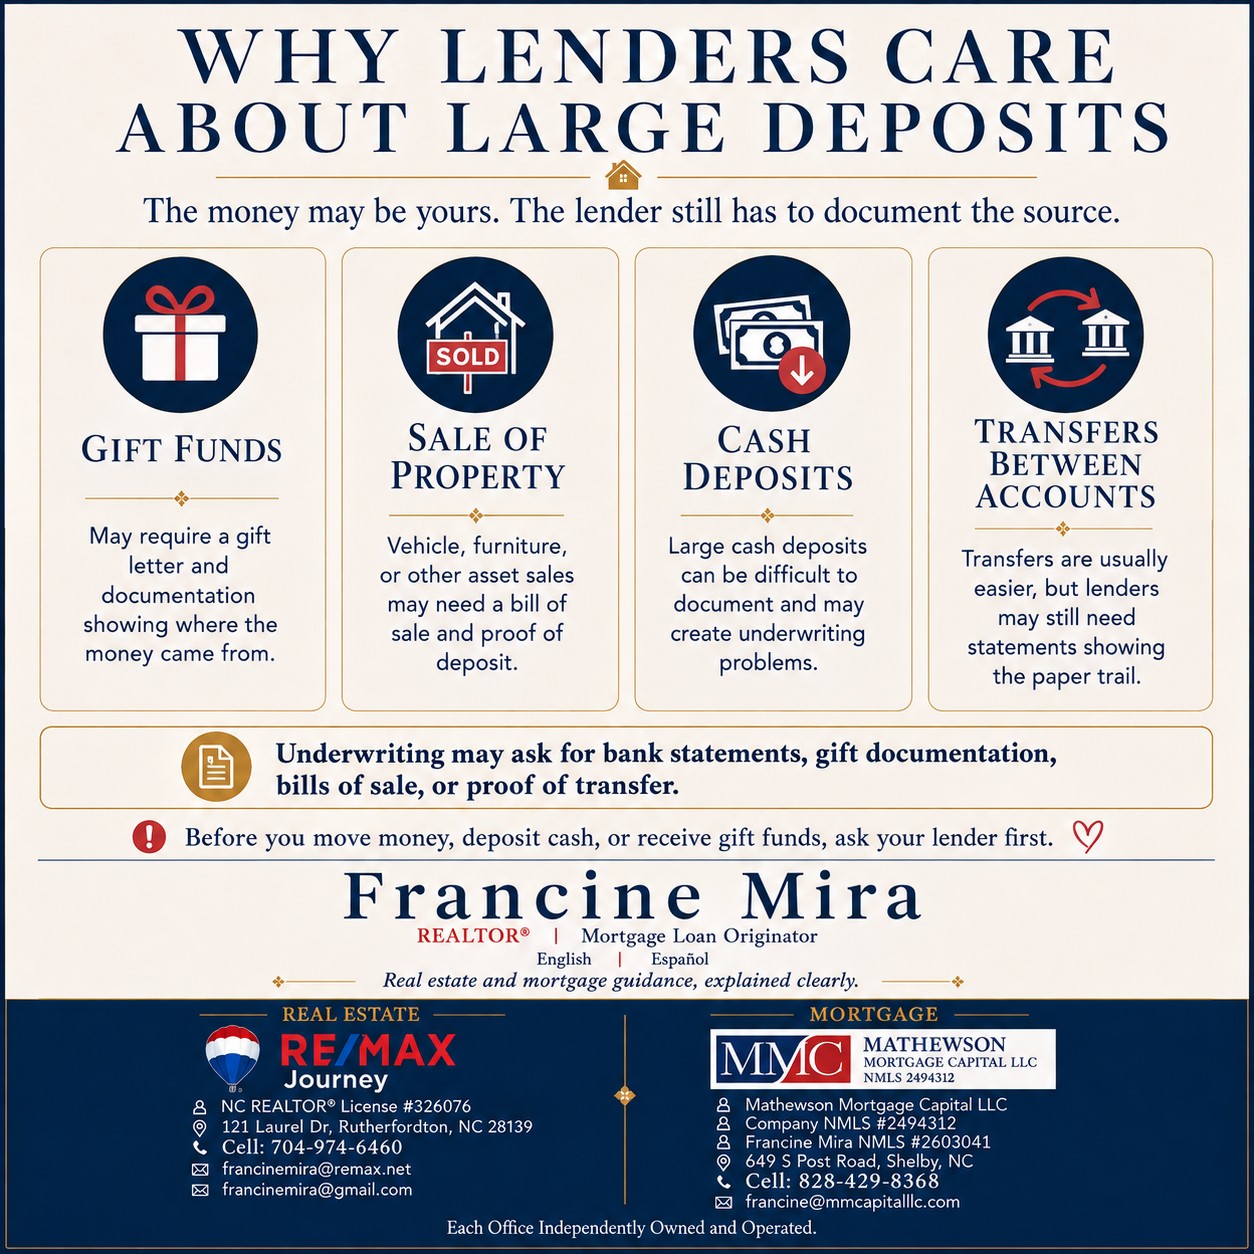
When you apply for a mortgage, underwriting is reviewing your assets to make sure the funds being used for your down payment, closing costs, and reserves are acceptable and properly sourced. So if a large deposit suddenly shows up in your bank account, they may ask for documentation.
Examples of Large Deposits
Examples can include:
- Gift funds
- Sale of a vehicle or other property
- Transfers between accounts
- Business income
- Cash deposits
- Money from family
- Proceeds from selling personal items
The easier the paper trail, the easier the conversation.
How Different Deposits Are Handled
For example, if you sold a vehicle, underwriting may ask for a bill of sale and proof that the funds were deposited into your account.
If the money was a gift, there may be gift documentation required.
If you transferred money from another account, they may need statements showing where the money originated.
And cash can be especially difficult because there may be no way to verify the source.
Talk to Your Lender First
This is why I tell buyers:
Before moving large amounts of money, depositing cash, receiving gift funds, or selling something to help with your home purchase, talk to your lender first.
A five-minute conversation before the deposit can save you from days of trying to recreate a paper trail later.
The money may absolutely be yours. The lender just needs to be able to document it.
Keep Your Finances Clean and Organized
If you are preparing to buy a home, start keeping your finances clean, organized, and easy to trace. It makes the mortgage process much smoother.
Francine Mira | Mortgage Loan Originator
Mathewson Mortgage Capital LLC
Company NMLS #2494312
Francine Mira NMLS #2603041
649 S Post Road, Shelby, NC
Cell: 828-429-8368
francine@mmcapitalllc.com
Francine Mira | REALTOR®
RE/MAX Journey
NC REALTOR® License #326076
121 Laurel Dr., Rutherfordton, NC 28139
Cell: 704-974-6460
francinemira@remax.net
francinemira@gmail.com
Each Office Independently Owned and Operated.
Want to see what you could qualify for?
Stop guessing. Check your readiness and, when you are ready, continue into the secure mortgage pre-approval process.