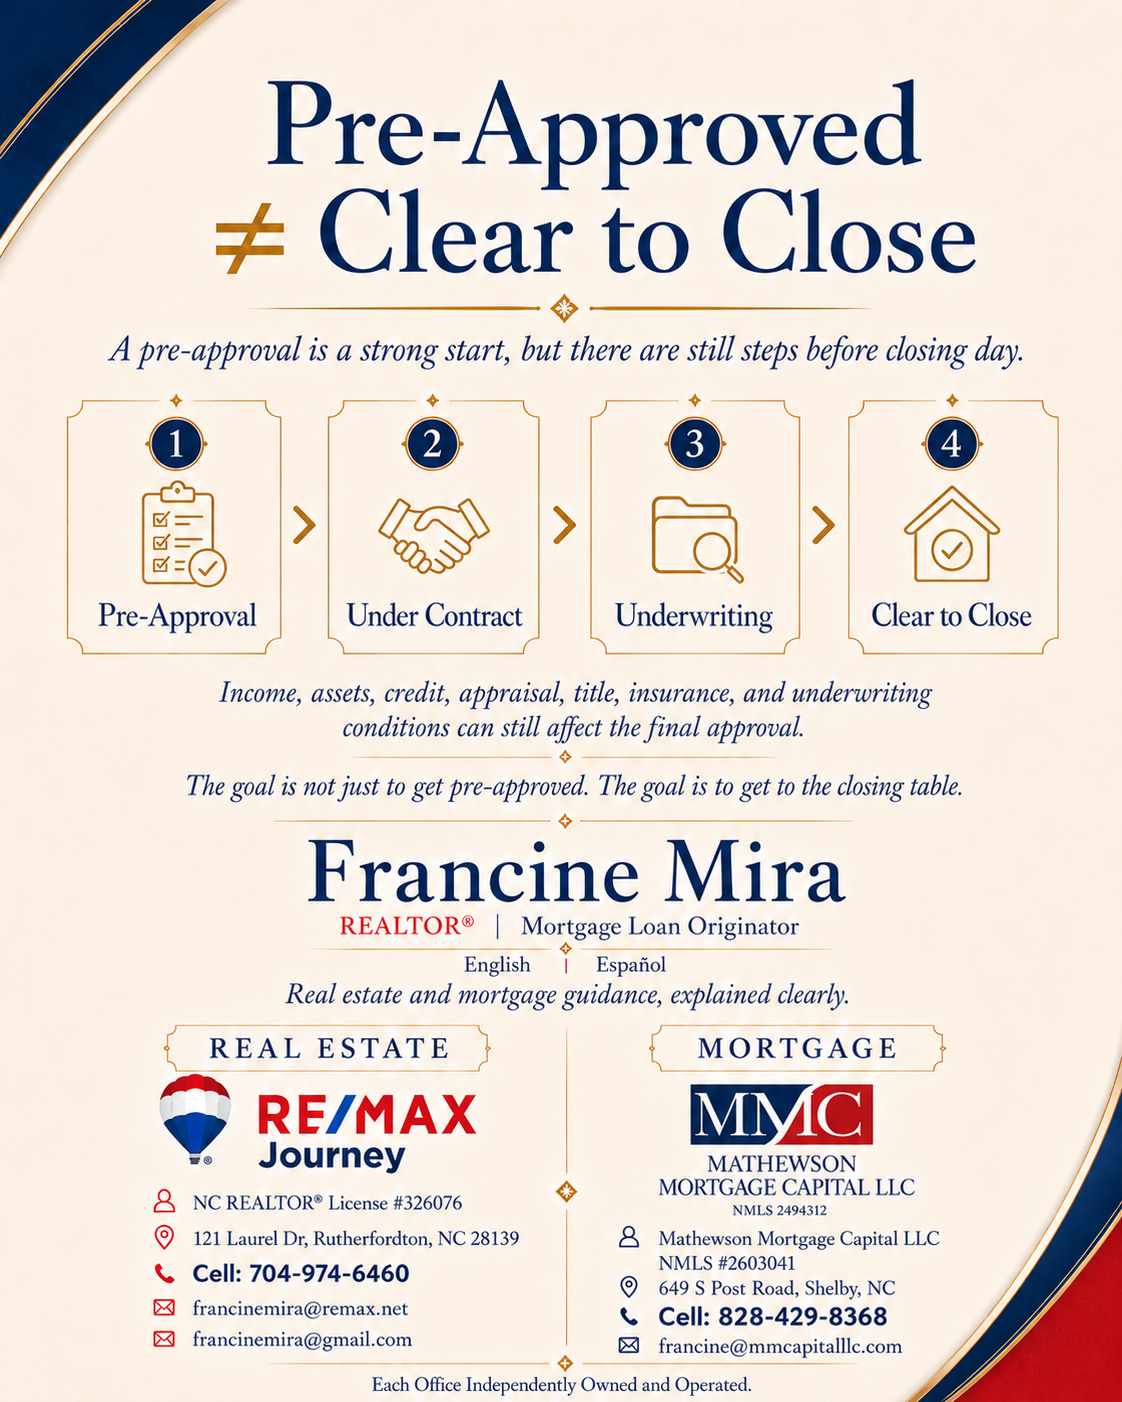
Pre-Approved ≠ Clear to Close: The Steps Between Pre-Approval and Closing Day
Quick answer
A pre-approval is a strong start, but there are still steps before closing day. Here's what buyers need to keep doing after pre-approval.
REALTOR® with RE/MAX Journey and Mortgage Loan Originator, NMLS #2603041. Bilingual homeownership education with a local focus on Rutherford County and Western North Carolina.
Pre-Approved ≠ Clear to Close: The Steps Between Pre-Approval and Closing Day
A pre-approval is a great start.
But it is not the same thing as being cleared to close.
This is one of those things I wish every buyer understood before going under contract.
A Pre-Approval Is Based on the Information Available at That Time
A pre-approval is based on the information available at that time.
Once you find a home and go under contract, there are still several pieces that have to come together.
Your lender may still need to verify things like:
- Income and employment
- Bank statements and available funds
- Updated credit and debts
- The property appraisal
- Homeowners insurance
- Title work
- Loan conditions from underwriting
- And sometimes additional documentation depending on the file
The 4 Steps to Closing
- Pre-Approval — Your initial qualification based on current information
- Under Contract — You've found the home and signed the agreement
- Underwriting — Verification of income, assets, credit, appraisal, title, and conditions
- Clear to Close — The final sign-off that your loan is ready to fund
Do's and Don'ts After Pre-Approval
That is why I tell buyers:
- Do not disappear after you get pre-approved.
- Keep sending requested documents quickly.
- Do not make major financial changes.
- Do not move large amounts of money around without explaining it first.
- And please, please do not assume that because you have a pre-approval letter, nothing else can change.
The Goal Is the Closing Table
The goal is not just to get pre-approved.
The goal is to get all the way to the closing table.
That takes communication, documentation, and a good team working together.
If you are thinking about buying a home, even if you are months away, starting early can make the process much smoother.
Francine Mira | Mortgage Loan Originator
Mathewson Mortgage Capital LLC
NMLS #2603041
649 S Post Road, Shelby, NC
Cell: 828-429-8368
francine@mmcapitalllc.com
Francine Mira | REALTOR®
RE/MAX Journey
NC REALTOR® License #326076
121 Laurel Dr, Rutherfordton, NC 28139
Cell: 704-974-6460
francinemira@remax.net
francinemira@gmail.com
Each Office Independently Owned and Operated.
#FrancineMira #MortgageEducation #PreApproval #HomeBuyingTips #FirstTimeHomeBuyer #Homeownership #RutherfordCountyNC #WesternNorthCarolina
Want to see what you could qualify for?
Stop guessing. Check your readiness and, when you are ready, continue into the secure mortgage pre-approval process.