10 Things Every First-Time Homebuyer Should Know
Quick answer
From hidden costs to negotiation strategies, here are the ten most important things to understand before buying your first home.
REALTOR® with RE/MAX Journey and Mortgage Loan Originator, NMLS #2603041. Bilingual homeownership education with a local focus on Rutherford County and Western North Carolina.
10 Things Every First-Time Homebuyer Should Know
Buying your first home is one of the biggest financial decisions you'll ever make. It's exciting, but it can also feel overwhelming — especially if you don't know what to expect. Here are ten essential things every first-time homebuyer should understand before diving in.
1. Know What You Can Actually Afford
That number a bank says you're "pre-qualified" for is not the same as what you can comfortably afford. Lenders look at your gross income, but you pay your mortgage with your net income. Factor in property taxes, insurance, HOA fees, maintenance, and utilities. A good rule of thumb: your monthly housing costs should not exceed 28% of your gross monthly income.
2. Your Credit Score Matters More Than You Think
Your credit score directly impacts your interest rate — and even a small difference adds up over 30 years. A score of 740+ typically gets you the best rates. Check your credit report months in advance, dispute any errors, and avoid opening new credit lines or making large purchases while house-hunting.
3. Get Pre-Approved, Not Just Pre-Qualified
Pre-qualification is a quick estimate. Pre-approval means a lender has verified your income, assets, and credit, and is committing to lend you a specific amount. Sellers take pre-approved buyers far more seriously — in a competitive market, it can be the difference between getting your offer accepted or ignored.
4. You Don't Need 20% Down
The 20% down payment myth keeps many people renting longer than they need to. Conventional loans can require as little as 3% down, FHA loans require 3.5%, and USDA and VA loans require zero down payment. Putting less than 20% down means you'll pay private mortgage insurance (PMI), but it may still be worth getting into a home sooner.
5. Don't Forget Closing Costs
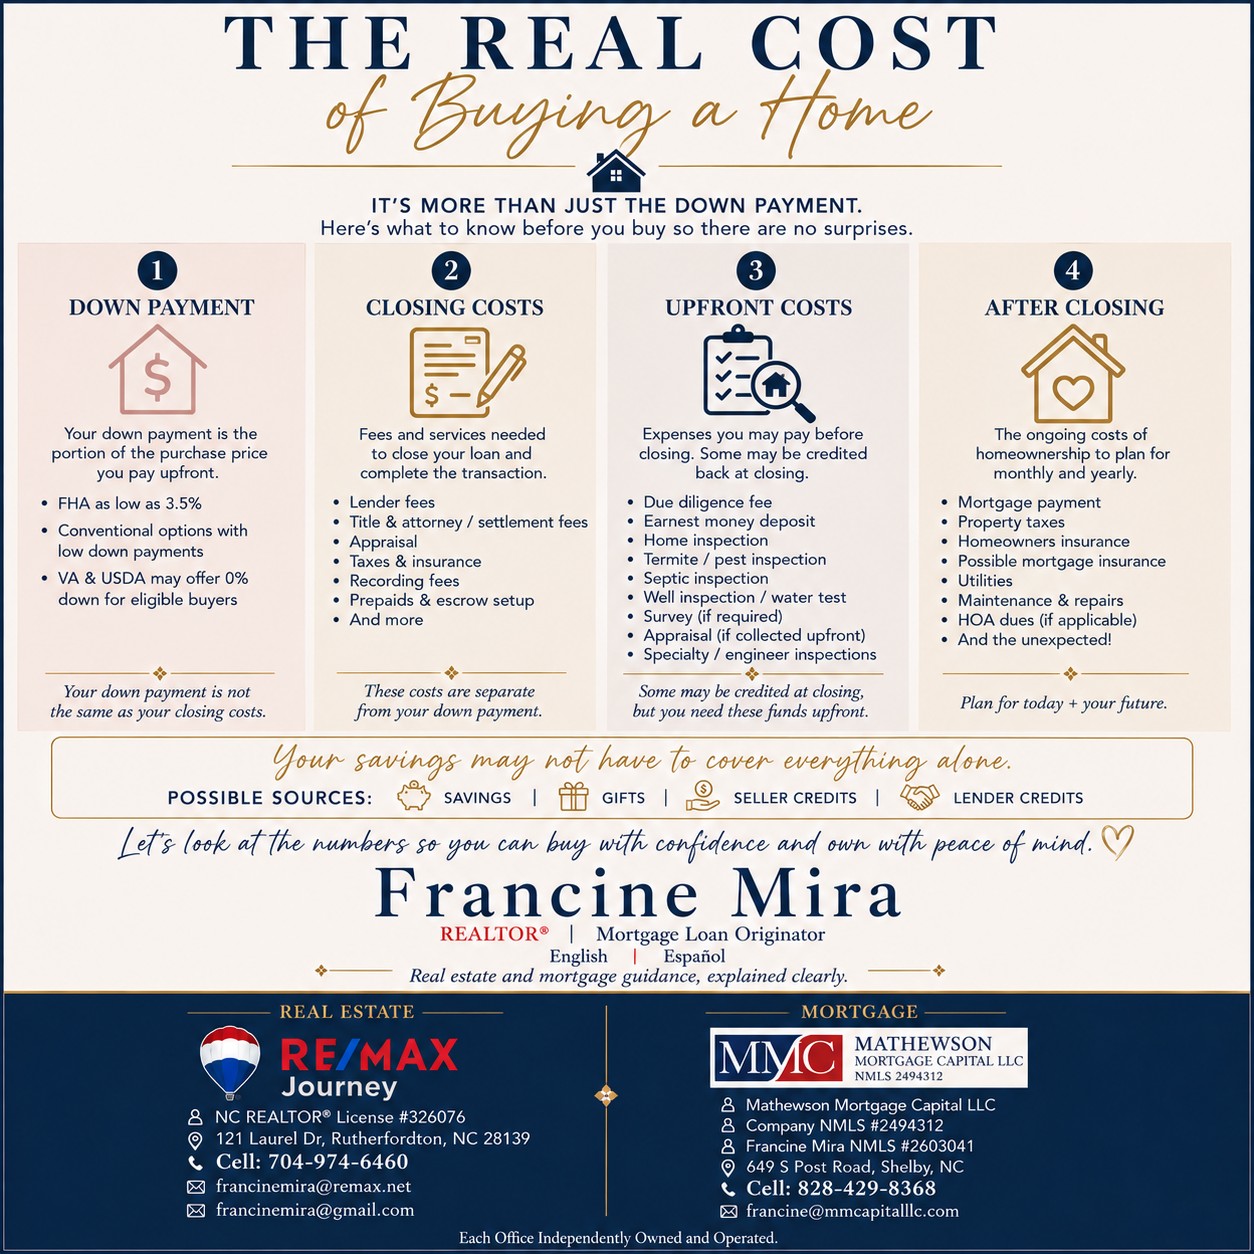
Closing costs typically run 2–5% of the loan amount and are due at closing — separate from your down payment. These include appraisal fees, title insurance, origination fees, and prepaid taxes/insurance. On a $250,000 home, that's $5,000–$12,500 you'll need on top of your down payment.
6. The Right Agent Makes a Difference
A good REALTOR® does more than unlock doors. They'll help you find homes that fit your needs and budget, negotiate on your behalf, guide you through inspections, and protect your interests throughout the process. Look for someone who knows the local market and communicates well.
7. Get a Home Inspection — Always
Even new construction can have hidden issues. A professional home inspection (typically $300–$500) can reveal problems with the foundation, roof, plumbing, electrical, and more. If issues are found, you can negotiate repairs or walk away. Never skip this step.
8. Think Resale Value
Even if you plan to stay for decades, life is unpredictable. Look for homes in desirable school districts, with good curb appeal, and in neighborhoods with stable or growing property values. Avoid homes with major negatives — busy roads, odd layouts, or deferred maintenance — unless you're prepared to accept the trade-offs.
9. Don't Make Big Financial Changes During the Process
Once you're under contract, do not open new credit cards, finance a car, change jobs, or make large bank transfers. Lenders re-check your credit and employment right before closing, and any changes can delay or derail your loan.
10. It's Okay to Walk Away
Falling in love with a home can cloud your judgment. If the inspection reveals major problems, the appraisal comes in low, or the seller won't negotiate on reasonable terms, be prepared to walk away. There will always be another house.
Ready to take the first step? Schedule a free buyer's consultation and I'll walk you through the entire process — from pre-approval to keys in hand.
Want to see what you could qualify for?
Stop guessing. Check your readiness and, when you are ready, continue into the secure mortgage pre-approval process.