Can I Use Gift Funds for a Down Payment or Closing Costs in North Carolina?
Quick answer
Often, yes. Many mortgage programs permit eligible gift funds, but the donor, purpose, documentation, and transfer of funds must meet the rules of the specific loan program and lender.
REALTOR® with RE/MAX Journey and Mortgage Loan Originator, NMLS #2603041. Bilingual homeownership education with a local focus on Rutherford County and Western North Carolina.
Can I Use Gift Funds for a Down Payment or Closing Costs in North Carolina?
For many buyers, the difference between “almost ready” and “ready to buy” is help from family or another eligible donor.
The good news is that gift funds are allowed under many mortgage programs, but there is a right way to document them.
What Is a Mortgage Gift?
A mortgage gift is money provided by an acceptable donor with no expectation of repayment.
That last part is important.
If the money has to be paid back, it is not really a gift and may need to be treated as debt.
Can Gift Funds Be Used for Conventional Loans?
Yes, subject to the applicable program rules.
Under Fannie Mae's current Selling Guide, eligible gifts can be used for down payment, closing costs, and in some circumstances reserves. For a one-unit principal residence, Fannie Mae does not require a minimum borrower contribution from the borrower's own funds solely because the LTV is above 80%; all required funds may come from an eligible gift when the transaction otherwise meets the rules.
Other property types and occupancy situations can have different requirements.
Can Gift Funds Be Used for FHA?
FHA also permits eligible gifts from acceptable sources.
HUD requires the lender to document the donor, relationship, amount, and the fact that no repayment is required. The lender must also document the transfer and source of funds according to FHA rules.
That means a random cash deposit labeled “gift” is not the same thing as properly documented gift funds.
What Documentation Might Be Needed?
Depending on the program and lender, expect some combination of:
- a signed gift letter,
- donor name and contact information,
- relationship to the borrower,
- gift amount,
- statement that repayment is not expected,
- evidence of the donor's acceptable source,
- proof of transfer to the borrower or closing agent.
The exact paper trail depends on the program.
Please Do Not Deposit a Large Gift First and Ask Later
This is one of the biggest practical tips I can give buyers.
If a family member plans to help you with a home purchase, talk with your mortgage professional before moving the money.
Why?
Because underwriting needs a clean paper trail. A properly planned electronic transfer or documented payment to the closing agent can be much easier to verify than trying to reconstruct a large unexplained deposit later.
Can a Gift Cover Everything I Need to Close?
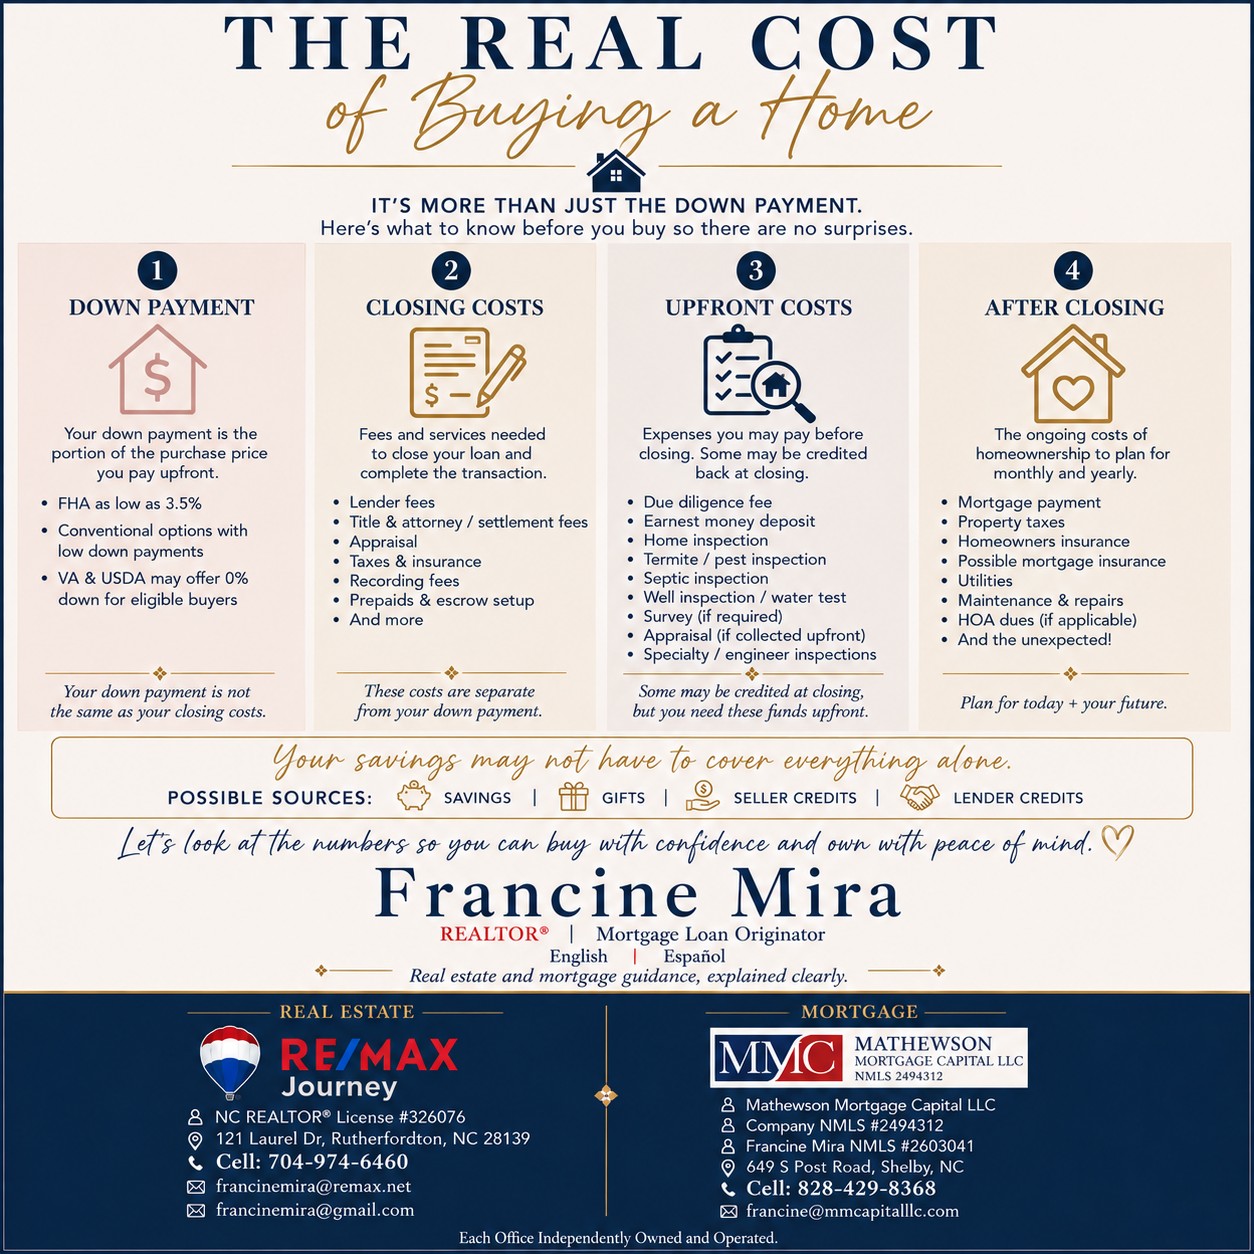
Sometimes it can cover a significant portion of the required funds, but the answer depends on:
- loan program,
- property type,
- occupancy,
- down payment requirement,
- closing costs,
- reserves if required,
- donor eligibility,
- lender underwriting.
There may also be North Carolina down-payment-assistance programs that can be evaluated alongside gift funds.
Gift Funds vs Seller Credits
These are not the same thing.
Gift funds come from an eligible donor.
Seller credits are negotiated contributions from the seller toward eligible closing costs and other permitted charges, subject to loan-program limits.
A good mortgage strategy may involve your own savings, eligible gift funds, assistance, seller credits, or a combination, but each source has its own rules.
If you are unsure whether you have enough saved, do not count yourself out. Start with the North Carolina Down Payment Assistance Guide and Mortgage Pre-Approval Guide.
Sources
- Fannie Mae Selling Guide, B3-4.3-04, Personal Gifts
- U.S. Department of Housing and Urban Development, FHA Single Family Housing Policy Handbook 4000.1
Francine Mira | Mortgage Loan Originator
Mathewson Mortgage Capital LLC | Company NMLS #2494312
Francine Mira NMLS #2603041
828-429-8368 | francine@mmcapitalllc.com
Gift-fund eligibility and documentation depend on the loan program, transaction, donor, lender, and underwriting findings. This article is educational and not a commitment to lend.
Want to see what you could qualify for?
Stop guessing. Check your readiness and, when you are ready, continue into the secure mortgage pre-approval process.