First-Time Buyer's Complete Guide to USDA Loans in NC
Quick answer
USDA Guaranteed loans may provide eligible North Carolina buyers with 100% financing for eligible primary residences in eligible rural areas. Property location, household income, borrower qualification, and current lender/program requirements all matter, and USDA does not set a universal minimum credit score for the Guaranteed program.
REALTOR® with RE/MAX Journey and Mortgage Loan Originator, NMLS #2603041. Bilingual homeownership education with a local focus on Rutherford County and Western North Carolina.
First-Time Buyer's Complete Guide to USDA Loans in NC
USDA financing can be a strong homebuying option in parts of North Carolina, especially when a buyer is considering an eligible rural or smaller-community property. But USDA is not a simple “zero-down loan for every rural home,” and it is not limited to first-time buyers.
The right way to evaluate USDA is to check the borrower, the household, and the exact property address before building your purchase plan around the program.
What Is a USDA Guaranteed Home Loan?
The USDA Single Family Housing Guaranteed Loan Program works through approved private lenders to help eligible households purchase qualifying primary residences in eligible rural areas.
For borrowers and properties that meet the program requirements, USDA Guaranteed financing may provide 100% financing, meaning a traditional down payment may not be required.
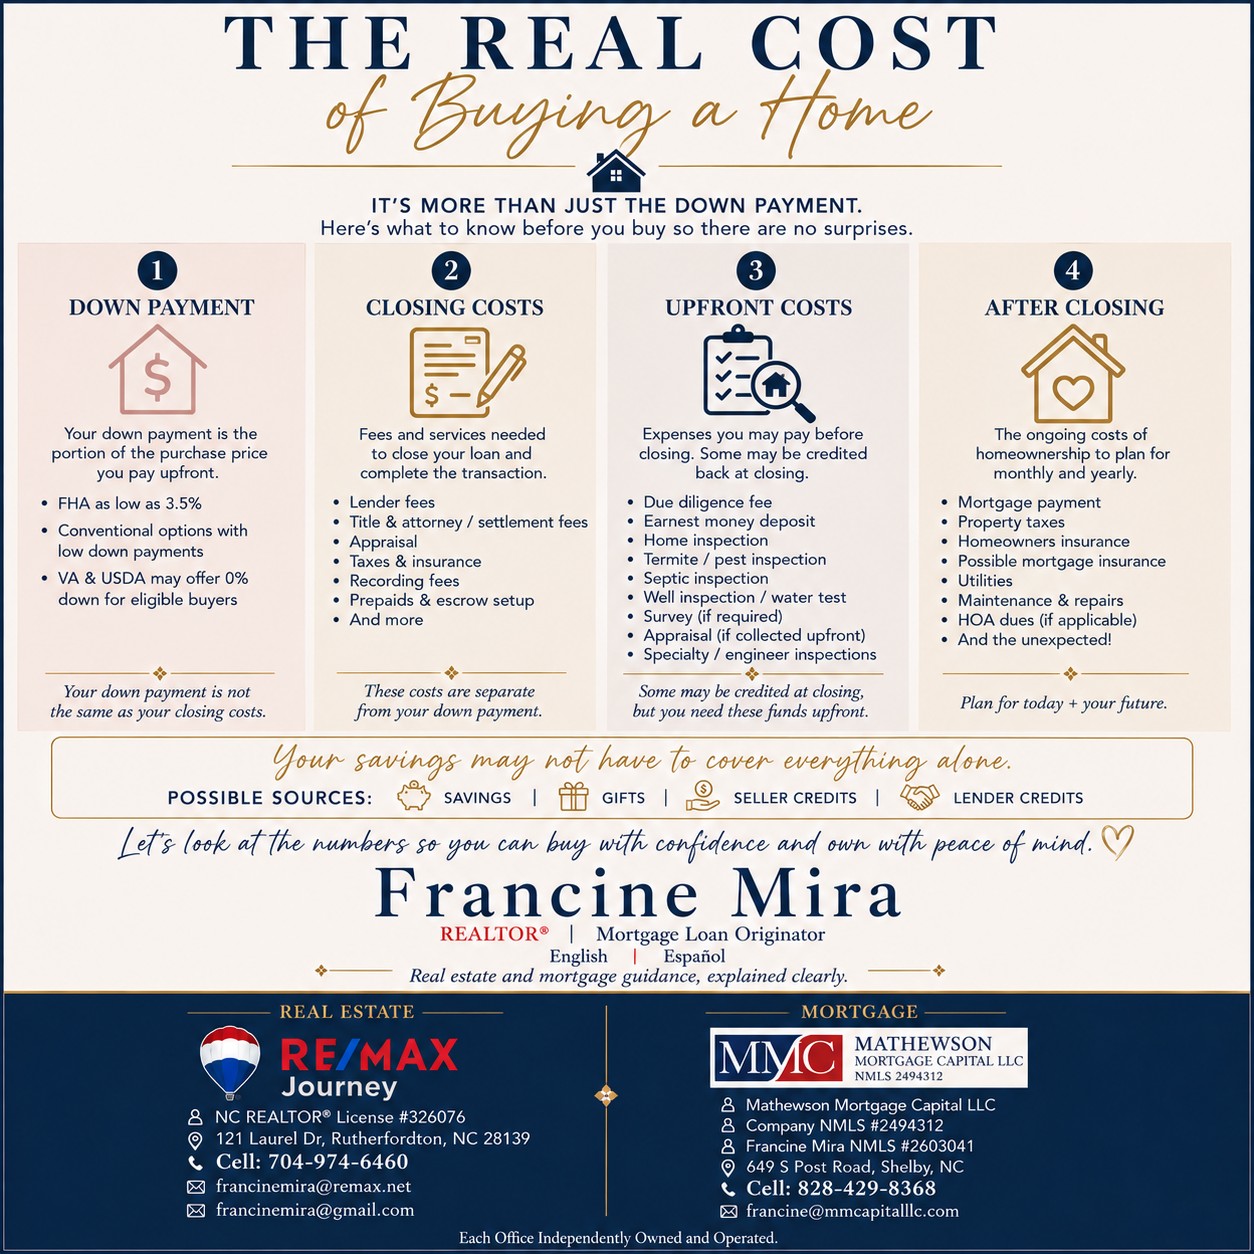
That does not mean a buyer will necessarily need zero cash. Closing costs, prepaid expenses, inspections, appraisal costs, due diligence money, earnest money, and other transaction expenses can still matter.
USDA Is Not Only for First-Time Buyers
You do not have to be a first-time homebuyer to use the USDA Guaranteed program. A buyer still has to meet the program’s current occupancy, income, credit, property, and other eligibility requirements.
Three Things Need to Work Together
1. The Property Address
USDA property eligibility is address-specific. Do not assume an entire town, ZIP code, or county qualifies just because it feels rural.
Before making financing assumptions, check the exact address using USDA’s current eligibility tools.
Check USDA property eligibility
2. Household Income
USDA uses household-income eligibility rules that are different from simply asking how much income a lender can use to qualify the mortgage.
Household composition and income can therefore affect program eligibility even when the borrower otherwise appears able to make the payment.
3. Borrower Qualification
USDA’s Guaranteed program does not publish one universal minimum credit score that automatically approves or disqualifies every borrower. Credit history, repayment ability, income, debts, underwriting findings, and lender requirements all matter.
A lender may have additional requirements or overlays, so do not rely on a single score you saw online as a guarantee of eligibility.
What About Debt-to-Income Ratio?
USDA underwriting evaluates the proposed housing payment and the borrower’s total monthly obligations. Published program guidance includes standard ratio benchmarks and allows qualifying considerations in certain situations, but the actual underwriting result depends on the complete file.
That is why a buyer should not self-disqualify based on a generic online DTI number without having the full scenario reviewed.
What Does USDA Cost?
USDA Guaranteed loans include program fees. USDA’s 2026 training materials list a current 1% upfront guarantee fee and a 0.35% annual fee, subject to current program rules and future change.
The upfront fee may be financed when permitted. The annual fee is calculated according to USDA program rules and is generally reflected in the monthly housing expense.
What Interest Rate Does USDA Offer?
For the Guaranteed program, USDA does not set one consumer mortgage rate for every borrower. Interest rates are determined by the individual lender and the loan transaction.
USDA Guaranteed loans use a 30-year fixed-rate term.
Be careful not to confuse the USDA Guaranteed program with USDA’s separate Direct loan program, which has different eligibility rules, rates, and administration.
What Types of Properties Can Work?
USDA’s current Guaranteed program guidance permits eligible new or existing residential property used as a permanent primary residence. Depending on program requirements, eligible structures can include detached homes, attached homes, condominiums, PUDs, modular homes, and qualifying manufactured homes.
The specific property still has to meet USDA and lender requirements.
Can a Manufactured Home Use USDA Financing?
Potentially, but manufactured-home transactions require additional review. Installation history, title status, land, foundation, age, HUD information, additions, and whether the unit has been moved can affect eligibility.
If you are considering a manufactured home, review the property before assuming the financing will work.
Read the North Carolina manufactured-home financing guide
USDA vs. FHA
Neither program is automatically better.
USDA may be attractive when the borrower and property qualify for eligible 100% financing. FHA may fit properties or borrowers that do not meet USDA’s location or household-income requirements. Monthly payment, mortgage insurance or program fees, cash to close, credit profile, property condition, and underwriting results should all be compared.
Compare FHA vs. USDA in North Carolina
What Should I Do Before Touring Homes?
Start with a financing review before becoming attached to a property.
A useful review should help answer:
- Is USDA worth considering for my borrower profile?
- Is my target area potentially eligible?
- What monthly payment range is realistic?
- How much cash might I still need even with 100% financing?
- Are FHA, Conventional, VA, or another available option worth comparing?
- Are there property characteristics that could affect financing?
Explore USDA loans in North Carolina or start with North Carolina mortgage pre-approval.
Francine Mira | Mortgage Loan Originator NMLS #2603041
Mathewson Mortgage Capital LLC | Company NMLS #2494312
Mortgage information is educational and is not a commitment to lend, Loan Estimate, pre-approval, or guarantee of approval. Program requirements, lender requirements, eligibility, rates, fees, and availability can change. Verify the current borrower and property scenario before relying on a financing strategy.
Current official program source: USDA Rural Development, Single Family Housing Guaranteed Loan Program.
Want to see what you could qualify for?
Stop guessing. Check your readiness and, when you are ready, continue into the secure mortgage pre-approval process.